• Skip to primary navigation
  • Skip to main content
Earmark CPE

Earmark CPE

Earn CPE Anytime, Anywhere

  • Home
  • App
    • Pricing
    • Web App
    • Download iOS
    • Download Android
    • Release Notes
  • Webinars
  • Podcast
  • Blog
  • FAQ
  • Authors
  • Sponsors
  • About
    • Press
  • Careers
  • Contact
  • Show Search
Hide Search

Blake Oliver

Private Equity’s Big Bet on Accounting Firms Is Starting to Look Shaky

Earmark Team · July 2, 2026 ·

CBIZ stock has lost half its value in the past year. Starbucks just killed its AI inventory counting tool after nine months of miscounts. And Microsoft, after investing $13 billion in OpenAI, had to cut off its own engineers from AI coding tools because costs went through the roof.

These stories from the latest episode of The Accounting Podcast paint a picture of where the accounting profession is heading, and it’s not what private equity investors or AI vendors promised.

CBIZ’s Stock Tells a Story About Private Equity’s Future

CBIZ is the only publicly traded accounting firm in the U.S., so its stock price is the closest thing we have to a market report card on the profession’s consolidation strategy. Right now, that report card shows failing grades.

“The stock price of CBIZ, Inc. today is $34.68. That is down 51% over the past year,” host Blake Oliver noted during the episode. When CBIZ bought Marcum at the end of 2024, the stock was at $78. It hit $90 in early 2025, then crashed to about $27 by March before recovering slightly.

What makes this even more interesting is that CBIZ isn’t alone. Co-host David Leary asked Blake to pull up Intuit’s chart for comparison. “Similar chart,” Blake confirmed. Intuit is down 53-54% over the same period. Meanwhile, the S&P 500 is up 28%.

The problem is what’s behind the stock price. CBIZ forecasts only 2% – 5% revenue growth for 2026. “That’s less than inflation. So basically, no growth,” Blake explained. “Why would investors be excited about buying stock in a company that’s not really growing much?”

Blake sees a more serious threat to large firms from smaller, more nimble competitors. “The larger the organization, the harder it is to change a business model or to integrate new technology,” he said. “I see smaller, more agile firms becoming a real threat to the large accounting firms. The smaller ones can integrate AI into their systems and switch their billing models.”

The math is simple but meaningful. AI lets a 10-person firm work like a 100-person firm. The traditional advantage of midsize firms (having an expert for everything) disappears when smaller firms can use AI to expand their capabilities.

Private equity firms typically look for efficiencies, not complete reinvention. “They figure out how to get marginally more efficient. They don’t completely reinvent the business model. That’s not what private equity is all about,” Blake explained.

When AI Meets Reality: Starbucks and Microsoft Learn the Hard Way

Starbucks spent nine months trying to make AI inventory counting work. The idea was that employees would walk past shelves, filming with an iPad, and AI from a company called NomadGo would automatically count everything. The company claimed 99% accuracy.

Reality hit hard. “Reuters reported the app often miscounted or mislabeled inventory, including confusing similar milk varieties or failing to recognize them,” Blake noted. Starbucks killed the project. Stores went back to counting by hand.

These failures hit the bottom line. “They were getting product shortages because they thought they had coffee, but didn’t have coffee to sell,” David explained.

Meanwhile, Microsoft discovered that AI coding tools come with a shocking price tag. Despite investing $13 billion in OpenAI and using AI to write 30% of its code, Microsoft had to cut off engineers from these tools because costs exploded. The same thing happened at Uber, where the CTO said they burned through a year’s worth of budgeted tokens in just four months.

The token problem is growing. Blake shared a striking statistic from Forbes: “Anthropic’s annualized net dollar retention exceeds 500%.” That means customers end up spending five times more than they initially expected.

“Nobody knows what they’re buying,” David said. “If I sign up for a monthly plan that gives me 20,000 tokens a month, it feels like enough. And then I’m six days into the month and I have to spend another 40 bucks for more tokens.”

“We’re going to hear a story like this in the next year,” David predicted. “Some firm will say, ‘Our five-person firm spent $300,000 on AI tokens, and we didn’t know it until it was too late.'” 

The Small Firm Revolution: XeroForce and AI Architects

While big firms struggle with their business models and AI costs spiral, something interesting is happening with smaller practices. Xero just launched XeroForce, a tool that could change the game.

“It’s a no-code AI agent builder that lets small businesses and accountants automate repetitive financial tasks using plain language, no technical skills required,” David explained. Unlike chatbots that give one-time answers, these are permanent automations that run on schedule.

Blake immediately saw the potential. “Every week, look at all transactions over $75 in any expense account, and then search my email for receipts and attach those receipts to the transactions. That’s a whole category of apps right there.”

“Accountants have engineer brains. You just don’t know how to write code. And if this can let you create ‘permanent’ code that runs routinely for a client inside Xero, it’ll help you scale,” David said, putting it in terms every accountant can relate to.

But tools alone aren’t enough. Firms need someone to manage this transformation. Donnie Shimamoto, CPA and founder and managing director at Intraprise Techknowlogies, calls this role an “AI architect.”

“Every CPA firm that’s big enough should create an AI architect role,” Blake said, comparing it to the cloud transition. “All the leading firms created these technology roles that were not IT. They were basically operations roles.”

An AI architect would handle security reviews, evaluate different tools, monitor token spending, and train the team. Without this role, firms risk security issues or shocking year-end bills.

For young accountants, Blake had direct advice. “If you’re a student or a young accountant and you want a job, learn this AI stuff. Every firm is going to be hiring an AI architect.”

What History Tells Us About What’s Coming

Blake drew a parallel to when electronic spreadsheets arrived. “The number of bookkeepers employed at accounting firms dropped by about half. We lost like a million bookkeepers over a generation,” he said. “What happened? We had more accountants and, in particular, we had a whole new category of job: financial analysts.”

His prediction for AI follows the same pattern. The number of traditional accountants will decline, but new roles will emerge. “Small businesses will be able to afford controllers and CFOs. They’ve always wanted them but could never afford to hire one.”

Both hosts emphasized the importance of experimenting now. David spent Memorial Day building a production assistant that saves him four hours a week. Blake spent two months creating a tool that automatically reconciles bank accounts.

“Don’t try to build anything groundbreaking,” David advised. “Just solve a simple problem that you have to deal with week after week.”

The Bottom Line

The accounting profession is changing fast, but not in the ways many expected. Large firms with private equity backing face serious challenges if they can’t reinvent their business models. AI implementation is proving harder and more expensive than promised. But smaller, agile firms that experiment with new tools and create AI architect roles could gain a huge competitive advantage.

“If you’re a firm with a few dozen people, you can now compete with firms that have hundreds of staff,” Blake said. That’s an opportunity for firms ready to embrace it.

Want to hear the full discussion, including how the hosts are building their own AI tools? Listen to the complete episode of The Accounting Podcast.

Accountants Rush to Adopt AI While Ignoring the Security Risks That Come With It

Earmark Team · June 19, 2026 ·

Nearly nine out of ten accountants using AI report positive returns. But another statistic is more troubling. Over half of accounting firms have experienced data breaches recently, yet fewer than half have guidelines for how AI handles sensitive financial data. The productivity gains are real, but so are the risks we’re ignoring.

Blake Oliver, host of the Earmark Podcast, recently sat down with David Jani, Senior Content Analyst at Capterra, to unpack Capterra’s 2026 Accounting Software Trends report. The survey of 500 U.S. accounting managers shows the profession has moved beyond testing AI and into territory where the gap between adoption speed and security readiness is becoming dangerous.


The Productivity Gains Are Real (With a Catch)

AI in accounting has crossed from experiment to standard practice. More than half of accountants now use AI in their accounting software, and it appears across all company sizes, not just enterprises with big tech budgets. As David noted, “We’ve gone beyond the point of it being companies testing the water with this stuff.”

The most common uses for AI are chatbots and AI assistants, followed by data entry automation and fraud detection. AI is also making headway in predictive analytics, cash flow forecasting, smart invoicing, and bank reconciliation. David described it as “a coalescence around analytics and process-driven tasks.”

The 89% positive ROI figure comes from two main benefits. Half of respondents cite productivity gains, and nearly as many report reduced errors. So firms see real time savings and quality improvements.

But 48% of accountants manually check every single AI output. Not spot-checking, but checking everything. And about a third catch errors in their AI outputs more than half the time.

How do you square 89% positive ROI with error rates that high? David’s practical take is AI is “creating some gains in some areas, creating some extra work in others,” but the net result stays positive. Even when you add review time, firms come out ahead. But he cautioned, “It’s important that businesses still keep a close eye on the ROI of these situations and confirm it is delivering those gains.”

Meanwhile, plenty of work remains manual. More than half of respondents still handle financial reporting through spreadsheets or manual processes. Accounts payable and receivable, billing, invoicing, and payroll are all heavily manual. And yes, 51% of accountants still use Excel or Google Sheets for financial data. As Blake observed, spreadsheets have survived 40 years and aren’t going anywhere soon.

The Security Gap No One’s Taking Seriously

While firms celebrate productivity wins, the security picture is alarming, and almost nobody seems concerned enough to act.

Consider 52% of accounting managers surveyed have experienced a data breach in the last two years. That’s more than half. While David doesn’t have data linking these directly to AI, what he found about AI and sensitive data should worry every firm leader.

“Most companies don’t have clear guidelines on how they use AI tools with sensitive data,” David revealed. Fewer than half (49%) have guidelines for employee and payroll information. Coverage of bank reconciliation and customer billing data is even lower.

The perception gap is striking. Nearly half view AI cybersecurity risk as “minor,” another 12% as “insignificant,” and only 3% as “critical.” This might be “why so many people don’t have guidelines. Unfortunately, they just don’t perceive the risks at play,” David said.

Blake painted a scenario that’s probably happening now. Someone uploads payroll reports into free ChatGPT, where the terms of service may allow the vendor to train on that data. “We really need to step up,” he said.

The risks go deeper. Blake raised the issue of prompt injection, which involves hidden text in documents that manipulates AI agents into leaking data or changing payment information. It’s sophisticated and hard to defend against. As David acknowledged, “It’s a very new and rather sophisticated way of extracting information from a company. We still don’t really know enough about it.”

David didn’t sugarcoat his advice. “Guidelines around this don’t seem like much, and obviously, everyone is rushing to get AI tools. But it’s a huge risk factor we need to address.”

AI Is Raising the Bar

If AI makes accountants more productive, you’d expect fewer jobs. But the data tells a different story, and it came as a surprise to David.

“Despite a lot of reports predicting the end of accountants, it’s not really what we found,” he said. Companies are adopting AI, but “it’s not necessarily affecting hiring decisions in the same way. A lot of companies are actually more focused on upskilling.”

Blake offered a historical perspective. The same panic hit when VisiCalc and Excel arrived 40 years ago, yet accounting jobs grew. When cloud computing transformed the industry, client accounting services didn’t shrink. Instead, it’s grown year over year for a decade.

The talent shortage persists, with 73% of firms reporting trouble with retention and hiring. The hardest roles to fill are mid-career positions. About a third struggle to find financial analysts, with specialized accountants (tax and cost accounting) close behind.

The paradox is AI actually increases the need for experienced professionals. Someone must review those AI outputs that are wrong half the time. Someone must understand the AI well enough to catch mistakes. Someone must manage the security implications. All that requires judgment and experience, and that’s exactly what’s hardest to hire right now.

The data backs this up. Upskilling existing staff is the dominant strategy at 40%, double the 21% using AI to fill staffing gaps. Traditional hiring sits at 31%, with graduate programs at 23%. The profession is betting on people, not automation, to solve its workforce problem.

Looking Ahead: Challenges and Choices

What keeps accountants up at night? Budgeting and forecasting in an uncertain economy tops the list, followed by figuring out how to use AI effectively. As David put it, firms are trying to understand AI “in a way that makes sense.”

David has specific advice for where firms should invest their AI dollars. Map investments to your particular needs rather than chasing trends. For general guidance, he pointed to data entry automation and predictive modeling tools, especially cash flow forecasting and analysis dashboards, as areas delivering the most value.

When asked to predict what might change by the 2027 survey, David hopes to see more firms with updated security guidelines. “I think as these tools become more mature, more people will update their guidelines, especially for handling sensitive data like payroll and cash flow,” he said.

A Gap Between Speed and Safety

The Capterra data shows the profession is getting AI both right and dangerously wrong. The 89% positive ROI is genuine. Firms are saving time and reducing errors, even after factoring in review burdens. But that headline obscures the fact that over half have experienced breaches, fewer than half have AI data guidelines, and most dismiss the cybersecurity risk as minor, even with threats like prompt injection that the profession barely understands.

AI isn’t solving the talent crisis either. It’s raising the bar for what accountants need to know, making experienced reviewers more critical while the mid-career talent shortage intensifies.

Firms must build guardrails, write guidelines, and invest in upskilling their people to successfully work alongside technology that’s powerful but imperfect.

Want to dig deeper into these findings? Listen to Blake’s full conversation with David on the Earmark Podcast, and earn free NASBA CPE while you’re at it. 

The New Earmark Is Here

Blake Oliver · June 5, 2026 ·

A Fresh Look for the Way You Work

We started Earmark because we believed continuing education for accounting and finance professionals could be a lot better than it was. Not a box to check at the end of the year, but something genuinely useful that fits into a real working life.

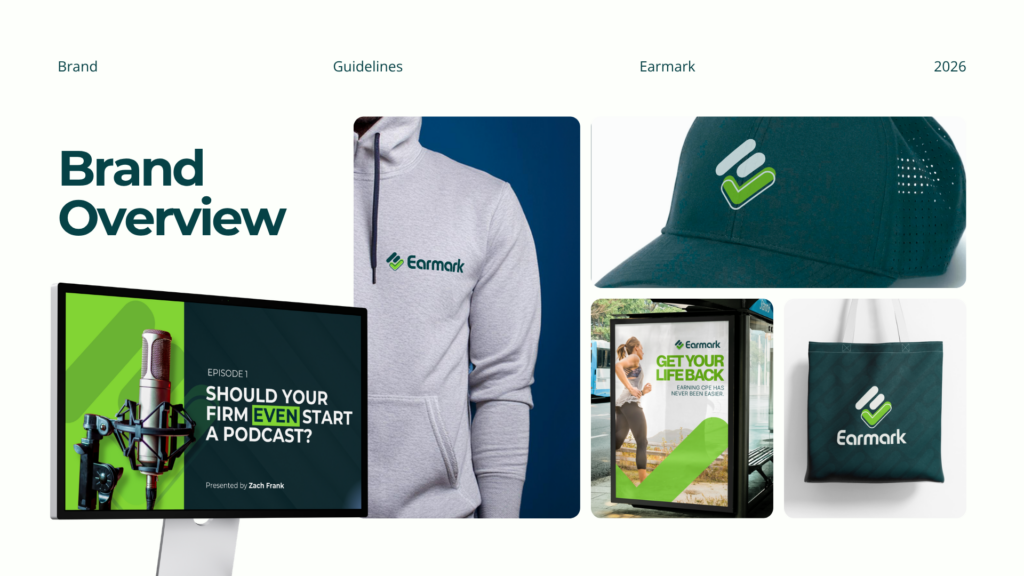
Today, I’m proud to introduce a new look for Earmark.

You’ll notice a refreshed brand, a cleaner visual identity, and a clearer voice. But a rebrand isn’t really about a logo. It’s about getting honest with yourself about who you are and where you’re going, and then making sure everything you put into the world reflects that. This new look is us doing exactly that.

Why now

For too long, CPE has been more complicated than it needs to be. Rigid formats, clunky systems, last-minute scrambles to track credits. It’s enough to make continuing education feel like a chore instead of what it should be: a way to do better work and grow with confidence.

Our mission has always been to change that, to transform an outdated model and deliver education that’s engaging, flexible, and actually worth your time. As we’ve grown into that mission, the brand needed to catch up. The new identity reflects the experience we’re building: modern CPE that’s clear, practical, and made for the way professionals work today.

Make your mark, on the go

Here’s what hasn’t changed: we still believe your education should respect your time. It should fit into a commute, a lunch break, or a quiet moment between meetings, not demand that you carve out a free afternoon you don’t have.

That belief is the heart of everything we do, and it’s why we want CPE to help you make your mark with education that travels with you. Because we think every professional has a real mark to make in this field, and better education is how the whole profession rises. That’s the future we’re working toward.

What to expect

Your account, your progress, and your certificates are all right where you left them. You’ll still find practical, mobile-first CPE and tools that make continuing education easier to manage for individuals, firms, and teams.

What’s new is the look, and it’ll roll out gradually across the app and the rest of the experience over the coming weeks. Behind the scenes, we’re doing what we always do: building, refining, and shipping updates to make Earmark better every time you open it. The fresh look is simply the part you’ll see first.

Welcome to what’s next

A rebrand is a milestone, but more than that, it’s a signal. For us, it signals a renewed commitment to building a better way to earn and manage CPE, and to elevating this profession through better education for everyone in it.

To the professionals, firms, partners, and educators who’ve shaped Earmark into what it is: thank you. We couldn’t have gotten here without you.

The new Earmark is here. Same mission, fresh energy, better CPE.

Welcome to what’s next.

Blake Oliver CEO, Earmark

Why the Most Profitable Accounting Firms of the Future Might Have No Employees at All

Earmark Team · May 31, 2026 ·

One guy. Zero employees. He spends 70% of his budget on technology.

Sam Leon runs The Millennial CPA in Richmond, Virginia, where AI does most of the tax prep work while he reviews and signs off. He just landed on Accounting Today’s 2026 Best Firms for Technology list, not by building a bigger team, but by proving you don’t need one at all.

Meanwhile, KPMG is shutting down its entire federal government audit practice after losing a $60 million Pentagon contract. They’re reassigning 450 employees and cutting another 400 from advisory. The old work is shrinking. The new AI, cyber, and forensics work is growing fast.

On this week’s episode of The Accounting Podcast, hosts Blake Oliver and David Leary discussed what these stories mean for the profession. They explored how AI is making the “firm of one” model possible, tested the new QuickBooks and Xero connections to Claude, and wrestled with a big question: If AI can replace so much labor, what happens to the people and the economy that depend on them?


The Solo Practitioner Who Turned AI Into His Staff

Sam Leon took a simple but radical approach to building his firm. AI handles the grunt work of tax return preparation, including creating workpapers, doing year-over-year comparisons, and mapping QuickBooks data to tax forms. He reviews everything and signs the returns. That’s it.

“I see AI as coming together to be a total tax preparer, and whoever signs the returns is the reviewer,” Sam told Accounting Today. He thinks of the AI as his junior preparer while he’s the senior reviewer.

The time savings are wild. Work that would take a human three to five hours, such as creating detailed tax workpapers from QuickBooks exports, takes AI five minutes. And Sam has no plans to hire. “I won’t hire until I hit a wall with my AI preparers and AI workflow managers,” he said.

Blake validated this approach based on his own daily use of Claude Cowork. “To do it as an individual is totally possible,” Blake said. “And so I expect we’ll see more of these firms of one, and you’ll be able to scale up and make a lot of money, because you don’t have to hire employees.”

David connected this to a broader trend he calls the “minimum viable-sized company.” The old playbook was simple: raise money, hire people, grow. “You don’t need that anymore,” David said. “The future winners are going to be small, highly efficient teams with strong strategic clarity. Not large organizations.”

Of course, there are questions. How much revenue does Sam actually make? How does he handle client communication and invoicing? Is he a software engineer or just really good at prompting AI? Blake and David want to get him on the show to find out.

The Tools Are Getting Easier, But Still Have Limits

Right now, Sam’s model works because he’s willing to configure AI tools himself. But that’s changing fast as AI gets built directly into the software firms already use.

Canopy just launched an AI “Coworker” feature across its practice management platform. David was initially skeptical when he saw the sample prompts, which included things like “list all my clients,” that you could see with one click anyway. But Blake highlighted the real value: scope-creep detection that analyzes your billing and emails to spot when you’re doing more work than you’re charging for, automatic workflow updates when disaster declarations change filing deadlines, and meeting notes that automatically create tasks with assignees and due dates.

“These AI agents in practice management are going to be hugely important,” Blake said. “They’re going to make practice management ten times more valuable.”

The big platforms are also opening up to AI. Intuit just released connectors linking Claude to QuickBooks, TurboTax, Mailchimp, and Credit Karma. Xero has one too. But Blake tested both and found them pretty limited. You can pull basic reports and import transactions, but you can’t actually analyze transaction-level data yet.

“If they don’t make connectors more robust, they’re kind of useless,” Blake said. Still, the direction is clear. As David put it, “Claude becomes like your central gear that’s spinning data out to these other spots.”

KPMG’s Federal Exit Shows Where the Profession Is Heading

While solo practitioners are using AI to do more with less, KPMG is learning what happens when you can’t adapt fast enough.

The firm just lost its contract to audit the U.S. Army. It was a $60 million annual deal they’d had for over a decade. The Army has never passed an audit, and now the Pentagon wants to restructure the whole approach. KPMG responded by shutting down the entire federal audit practice and reassigning 450 people.

But that’s not all. They’re also cutting 4% of U.S. advisory staff, or about 400 people, mostly in regulatory risk and financial services consulting. These cuts continue a pattern that started in 2023.

Instead, KPMG is investing in AI, cyber, forensic services, and managed services. Traditional audit work is shrinking, while tech-enabled services are growing.

The Big Risk 

If companies use AI mainly to eliminate jobs, who’s going to buy their products?

Christine Kuglin and Bright Ikwetie wrote about this in Accounting Today, calling it the “AI efficiency paradox.” Businesses get more efficient by replacing workers with AI, but they’re also eliminating the incomes that drive consumer spending. It’s a potential death spiral. Less spending means less revenue, more layoffs, and more AI. Rinse and repeat.

The economic data is confusing. Weekly jobless claims just hit 189,000, the lowest in more than five decades. Yet manufacturing employment is down 88,000 jobs year over year. How can unemployment be so low when we keep hearing about layoffs?

“Is this just lagging?” Blake wondered. “Are these workers just finding jobs in other parts of the economy or maybe working for themselves?”

For accounting specifically, the demand for talent remains strong. Intuit analyzed LinkedIn data and found that both tax and accounting roles are “very hard to hire” nationally. They’re actively recruiting with flexible, remote-first benefits, which is exactly what the Big Four firms are cutting.

What This Means for Your Firm

The lesson from Sam is that one person can now deliver what used to require a team. The same principle scales up. A small firm can compete with a large one, and a mid-size firm can offer enterprise-level services.

But don’t use AI just to do the same work with fewer people. Use it to do work you couldn’t do before. As Blake put it, “The growth opportunity in accounting is advisory-type services. And AI paired with expert humans is just so incredibly powerful for doing advisory work like fractional CFO services, M&A advisory, and cost segregation studies.”

David sees another opportunity in helping clients “vibe code” custom apps instead of stacking expensive SaaS subscriptions. “I am confident that accountants could vibe code,” he said. “The old stack of app stacking is going to go away. You’re just going to help your client build the app they need.”

The tools are here. The demand is there. The question is whether firms will use AI to shrink or to grow. Firms that use AI to expand what’s possible rather than just cut costs will set the terms for everyone else.

Want to hear Blake test the QuickBooks-Claude connector live? Curious about how much Sam actually makes? Listen to the full episode of The Accounting Podcast for all the details, plus discussions on new IRS whistleblower rules, tariff refund lawsuits, and why procrastinating on AI adoption might actually pay off.

Stop Losing Money on Cleanup Work by Automating the Parts That Don’t Need You

Earmark Team · May 31, 2026 ·

Cleanup and catch-up work is among the most in-demand services accounting firms can sell, and among the hardest to deliver profitably. That was the starting point for a recent webinar led by Megan Reid, a 15-year accounting veteran who started in Big Four, moved through private industry, and now works on the firm enablement team at Digits.

In the webinar, Megan demonstrated how AI-native accounting tools can transform cleanup engagements from time-intensive projects into scalable service offerings. She built a client file from scratch, imported raw PDF bank statements, and walked through an entire cleanup workflow in real time.

Why cleanup work kills profit margins

“Cleanup is obviously valuable work and it’s hard to scale,” Megan said, framing the core challenge clearly. New clients almost always arrive with some sort of mess to clean up. Maybe you have 18 months of uncategorized transactions or transactions that haven’t been posted from the bank feed. You want to take the engagement, but you know it’s going to be hard to make it profitable.

“We always uncover more skeletons in the closet than we think,” Megan noted during the demonstration. If you’re billing fixed fees, you get squeezed by unpredictable hours. Clients want fast turnarounds. Your teams are leaner. “You’re asked to do more with less,” she said.

“Business owners need that work to be done,” Megan pointed out. But the question is “whether or not your workflow lets you take them profitably.”

Breaking down a traditional cleanup shows where the hours go:

  • Gathering data
  • Importing it or connecting feeds
  • Categorizing tons of transactions
  • Reconciling accounts
  • Resolving exceptions
  • Making adjusting entries
  • Reviewing everything with your client
  • Delivering the final report

“In a typical 12-month cleanup or catch-up, you spend the majority of your time categorizing and reconciling transactions,” Megan explained. These tasks are also “the most repetitive, pattern-based parts of the job, which is exactly what AI is good at.”

From blank file to categorized transactions

Megan started her demonstration with a completely blank client file, essentially just an empty ledger. She then showed how to handle a common scenario in which a new client hands over a stack of PDF bank statements with no bank login credentials.

She dragged and dropped the first PDF bank statement directly into Digits. “It is extracting all that data from the bank statement, booking it and categorizing it as well,” Megan explained as the system processed the document.

The AI extracted transactions, identified vendors and customers (called “parties” in Digits), populated company logos and descriptions, attached website links, and categorized each transaction into the appropriate account. Megan noted the system pulls from models trained on “more than 800 trillion dollars’ worth of transactions.”

After uploading statements for June through October, hundreds of transactions flowed in. When processing finished, only 12 were flagged for review. “Instead of manually clearing bank feeds,” Megan said, “come here and look at the exceptions.”

These were transactions that required confirmation. Megan clicked into one from Swift Courier Services. The AI suggested “contractors and consultants.” She confirmed it with one click.

From there, the system natively learned from that categorization. It immediately found two similar transactions and offered to update them together. The exception list dropped from 12 to 8 in seconds.

Bank reconciliation without the manual work

Megan demonstrated three ways to get bank statements into the system for reconciliation. You can connect directly to banks like Mercury, Wells Fargo, Chase, and US Bank, which pull statements automatically via API. You can drag and drop PDF statements anywhere in the product. Or you can use email ingestion, where each client gets a unique email address to forward statements.

She uploaded the June statement by dragging it onto the reconciliation screen. The system read the PDF, extracted every line item, and verified each against the ledger. Megan explained that the system uses “pixel bounding boxes” to match statement entries to ledger entries.

June needed one manual step: adding a beginning balance entry that the system couldn’t infer without a connected bank account. Megan created the entry directly in the reconciliation screen. “Unlike legacy systems, where you may have to have three different tabs open and make changes and then come back and refresh, everything can be done directly in here.”

Then she uploaded July’s statement and navigated away. When she returned, it was done. “The statement was uploaded by me. The auto reconciliation was kicked off by Digits and even finalized by Digits,” she showed in the timeline view.

For larger cleanups, Megan recommended uploading multiple statements at one time. Handle any beginning balances in the first month, then subsequent months often complete automatically.

Review tools that surface what matters

Even with AI handling categorization, accountants still need to review and sign off. “It doesn’t replace the accountant. It just removes that tedious work so that you can focus on those judgment calls,” Megan emphasized.

She demonstrated several review approaches. The general ledger view shows all transactions organized like a trial balance, including assets, liabilities, equity, revenue, and expenses. You can filter by status, amount, source, department, or location. Bulk updates work on hundreds of transactions at once.

Megan said the vendors and customers views are her favorite. They each flag two critical items:

  • New vendors or customers: Any vendor (or customer) the AI sees for the first time in your selected period
  • Split categorizations: Vendors (or customers) whose transactions appear in multiple categories

“I just need to have eyes on things it has not seen before,” Megan explained. Even if the AI categorized with high confidence, you have final review and say on how it was categorized..

For transactions needing client input, the collaboration happens in one place. Megan showed how to comment on any transaction: “Hey client, what is this for?” The client receives an email with a link, can respond directly in Digits or reply to the email, and the response appears on the platform. “All the collaboration is centralized in one location,” she said, “instead of you having to manage a ton of emails and download Excel files.”

Delivering professional reports, not data dumps

The final step Megan demonstrated was creating custom reports. While the financials inside Digits update live as transactions flow in, cleanup engagements need a formal deliverable, a static document that locks the numbers in place.

Megan built one on screen. She added a cover page, used AI to draft an executive summary, embedded links to the client’s checklist, and configured the financial statements with period comparisons and trend lines. The system includes “hover to discover” insights that show period-over-period changes and what drove them.

When you need to make adjustments after sending a draft, you create a new version. “Any adjustments you’ve made in Digits will then update directly to this report,” Megan explained. Publishing the final version removes the draft watermark and notifies the client.

The platform tracks everything, including when you created the report, when you published it, when the client viewed it, and all comments from either party. You have a complete record of the deliverable and the conversation around it.

“We’ve done 12 months of cleanup in an hour and a half instead of days,” Megan concluded.

What this means for your firm

The key takeaways from Megan’s demonstration show how cleanup engagements can become profitable:

  • AI categorizes the vast majority of transactions automatically, flagging only true exceptions
  • Bank reconciliations can run automatically when you upload statements
  • The system learns instantly from every correction without rules to build or maintain
  • Your time shifts to reviewing anomalies, making judgment calls, and delivering polished reports

One practical consideration came up during Q&A. When asked about importing messy QuickBooks Online data, Megan confirmed that direct QBO migration exists but cautioned, “You maybe don’t want the AI to learn off of really messy data. You maybe just want to start fresh.” The system uses imported data for baseline training, so starting clean might make more sense for particularly messy files.

For firms trying to grow, this changes the economics of client acquisition. Every prospect with messy books becomes an opportunity rather than a capacity problem. When you can handle cleanup work profitably, predictably, and consistently, you can say yes to more engagements while maintaining margins.

Watch the full on-demand webinar to see Megan’s complete demonstration from blank file to published financials. If you have cleanup engagements in your pipeline right now, consider what your workflow could look like when the repetitive work is automated.

  • « Go to Previous Page
  • Page 1
  • Page 2
  • Page 3
  • Page 4
  • Page 5
  • Page 6
  • Interim pages omitted …
  • Page 26
  • Go to Next Page »

Copyright © 2026 Earmark Inc. ・Log in

  • Help Center
  • Get The App
  • Terms & Conditions
  • Privacy Policy
  • Press Room
  • Contact Us
  • Refund Policy
  • Complaint Resolution Policy
  • About Us